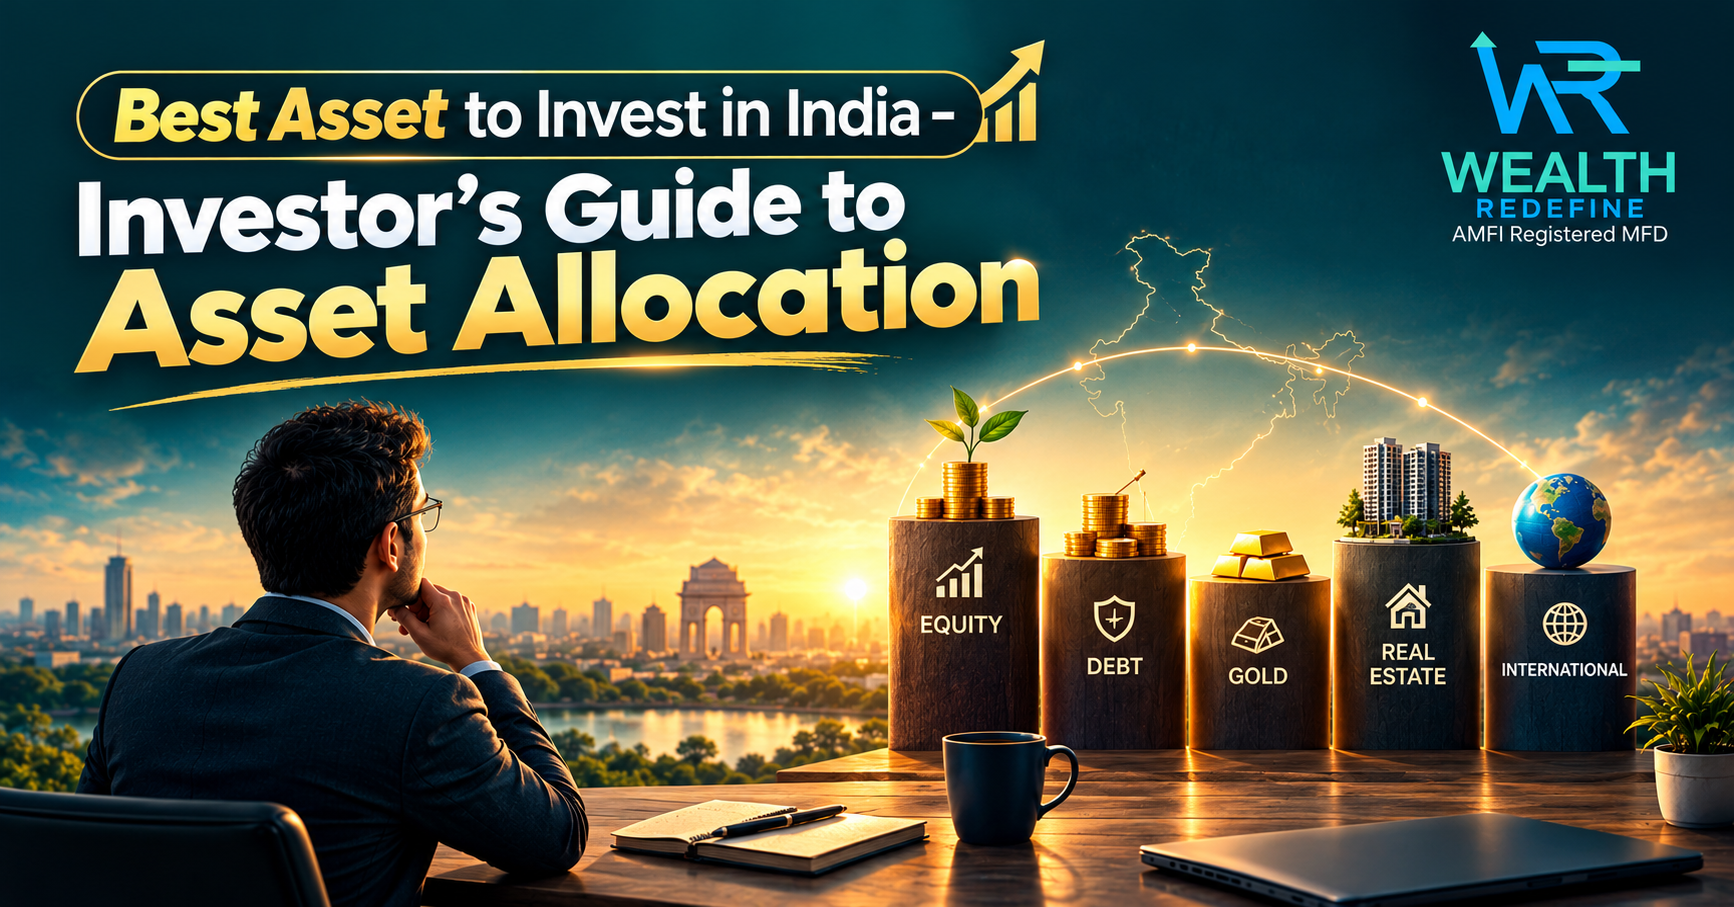
The honest answer is that no single asset is the best every year. In 2025, gold rose 72% and silver 122%, while the Nifty 500 gained only 7%, according to 1 Finance Research. For most Indian investors in 2026, a mix of equity, debt and gold, built yourself or through a multi asset fund, is more dependable than betting on one asset.
If you are a working professional who keeps asking where the next SIP should go, this guide gives you a clear way to decide. It covers asset classes, multi asset funds, tax math and the mistakes most articles skip.
What is the Best Asset to Invest in 2026?
There is no single best asset to invest in 2026. Equity gives long-term growth, gold cushions market falls, and debt gives stability. The right mix depends on your goal date, risk comfort and tax bracket. Spreading money across all three beats guessing last year’s winner.
Why last year’s winner is a trap. The last full year shows how fast leadership changes:
| Calendar year 2025 | Return |
| Silver | 122% |
| Gold | 72% |
| Nifty 500 | 7% |
Source: 1 Finance Research, Global Economic Outlook 2026 (25 February 2026).
A 72% jump in one year is not a repeatable return. Over 20 years, gold has delivered roughly 12% a year in rupee terms (FundsIndia, as on 31 August 2026). Investors who buy after a rally often buy near the top.
The macro backdrop matters too. The same 1 Finance outlook projected India’s GDP growth at 6.7% and average inflation at 3.9% for calendar 2026, with room for a 50 to 75 bps repo rate cut by the RBI. These are forecasts, not guarantees.
What is the Best Asset Class to Invest in 2026?
The best asset class to invest in 2026 is the one that matches your time horizon: equity for goals beyond 5 years, debt for goals under 3 years, and gold as a smaller diversifier. Multi asset funds combine these in one scheme.
| Asset class | Best suited for | Risk | Liquidity | Tax (as of FY 2026-27) |
| Equity mutual funds | Goals 5+ years away | High | High | STCG 20% under 12 months; LTCG 12.5% above ₹1.25 lakh after 12 months |
| Gold ETFs | Diversification, inflation cushion | Medium to high | High | STCG at slab rate; LTCG 12.5% after 12 months, no ₹1.25 lakh exemption |
| Debt funds and FDs | Goals under 3 years | Low to medium | Medium to high | Slab rate (debt funds bought after 1 April 2023) |
| Multi asset funds | One-fund diversification | Medium to high | High | Depends on equity share (see tax section below) |
Tax rules are time-sensitive. Rates shown are as of 2026; confirm with the latest Income Tax Department notification. Budget 2026 left mutual fund capital gains rates unchanged, per published tax guides.
Silver deserves a note. It rallied 122% in 2025 on industrial demand and supply deficits, but that also makes it one of the most volatile options.
Read Also: Why multi-asset funds are your best bet amid market fluctuations?
What are Good Asset Investments? Best investment ideas for 2026 by goal
Good asset investments match a goal, a time frame and a risk level: equity funds for long-term growth, debt funds or FDs for short-term needs, gold for diversification, and multi-asset funds for one-fund balance. Rank them by goal, not by last year’s return.
Here are investment ideas, sorted by when you need the money:
- Emergency money (any time): liquid or savings options, not market-linked assets.
- Under 3 years: debt funds, FDs or short-duration options.
- 3 to 5 years: balanced hybrid or multi asset funds, which limit equity swings.
- 5 years and beyond: equity SIPs, plus a gold slice for diversification.
A common mistake is holding one asset for every goal. A house down payment due in 2 years should not sit in the same bucket as retirement money due in 20.
What is a Multi Asset Allocation fund?
A multi asset allocation fund is a hybrid mutual fund that must invest at least 10% each in three asset classes, typically equity, debt and gold, under SEBI’s fund categorisation. The fund manager shifts weights between them, so you get diversification and rebalancing inside one scheme.
Diagram 1 (insert): flow from your SIP to one fund holding equity, debt and gold, with the manager rebalancing. See the Publishing Kit.
These funds earn returns from several sources at once:
- Equity: long-term growth from company earnings
- Debt: interest income and stability
- Gold and silver: a cushion when equity markets fall
- Rebalancing: the manager trims what has run up and adds to what has lagged
Not all multi asset funds are alike. Equity share ranges widely. One scheme may hold 65% to 80% in equity, while another sits between 35% and 65%. Two funds with the same category name can behave very differently.
Are Multi Asset Funds a Good Investment in 2026?
Multi asset funds can be a good investment in 2026 for investors who want equity growth with a gold and debt cushion in one fund. They are not risk-free: returns depend on the equity share, and a fund can still fall 10% or more in a sharp market drop.
The category has clearly gained investor attention:
- In July 2026, multi-asset allocation funds saw net inflows of ₹3,752 crore, more than thematic and sectoral equity, multi-cap, and large and midcap categories (Upstox, August 2026).
- The four largest schemes by AUM are ICICI Prudential Multi-Asset, Nippon India Multi Asset Allocation, SBI Multi Asset Allocation and Kotak Multi Asset Allocation.
Common misconception: multi-asset means low risk. Franklin India Multi Asset Allocation Fund recorded a maximum drawdown of 11.55% between 29 January 2026 and 23 March 2026 (Arthgyaan data). Diversification reduces risk. It does not remove it.
Also remember that recent category returns were helped by the 2025 gold and silver rally. Do not assume that tailwind repeats.
Which are the Best Multi Asset Funds to Invest in 2026?
The best multi asset mutual funds to invest in 2026 are the ones with a consistent track record, a stable fund manager, reasonable costs and an equity share that suits your risk level. Compare at least 3 years of data across schemes instead of picking the latest top performer.
How to read the landscape. Funds broadly fall into three styles:
| Style | Typical mix | Behaviour | Example of approach |
| Equity-led | 65% to 80% equity, 10% to 25% gold, 10% to 25% debt | Higher growth, higher swings | Union Multi Asset Allocation Fund launch mandate |
| Balanced | 35% to 65% equity | Moderate swings | Hybrid-style multi asset schemes |
| Arbitrage-led | Arbitrage for equity and gold or silver exposure | Lower volatility, lower upside | Edelweiss Multi Asset Allocation approach |
Example of how to read data. As of 11 September 2026, Nippon India Multi Asset Allocation Fund showed 3-year annualised volatility of 9.19% against a category median of 8.28%, and beat the category average across 1, 3 and 5 years (Arthgyaan). Higher volatility alongside higher returns is a trade-off, not a free lunch.
Funds often screened by platforms include Quant, Nippon India, UTI, SBI, Tata, HDFC and Axis multi asset schemes (INDmoney listing, 2026). This is for information only and is not a recommendation. Check the latest factsheet before investing.
How to choose mutual funds for SIP: which is the best multi asset allocation fund to invest in 2026?
To choose mutual funds for SIP, match the category to your goal, check 3 to 5 year rolling returns, compare volatility with the category median, review costs and fund manager tenure, and confirm tax treatment. For the best multi asset allocation fund to invest in 2026, also check the equity share.
Use this checklist:
- Check average equity exposure. It determines both risk and tax treatment.
- Read the asset mix history in the factsheet. See how much the gold share changed.
- Compare rolling returns over 3 and 5 years, not just 1 year.
- Compare volatility with the category median. A fund far above it needs a higher risk appetite.
- Look at maximum drawdown. Ask whether you could hold through a fall like that.
- Review expense ratio, plan type and manager tenure, as disclosed under SEBI rules.
AMFI data and each AMC’s monthly factsheet are the primary sources for these checks.
What are Mutual Funds Investment Plans for Beginners?
Mutual funds investment plans for beginners usually start with a monthly SIP in one diversified fund, such as a multi-asset or balanced hybrid fund, then add a pure equity fund after 12 to 24 months once volatility feels manageable. Start small, automate it and stay invested for 5 years or more.
| Stage | Structure (illustrative, not advice) | Suits |
| Starter | One multi-asset fund SIP | First-time investors |
| Building | Multi asset fund plus one diversified equity fund | 1 to 2 years of SIP experience |
| Goal-based | Separate debt fund for goals under 3 years | Specific near-term goals |
Simple SIP math (assumed returns, not guaranteed): a SIP of ₹10,000 a month for 10 years means ₹12 lakh invested. At an assumed 10% a year it grows to about ₹20.7 lakh. At an assumed 12% it grows to about ₹23.2 lakh.
To begin:
- Complete KYC once.
- Write down the goal and the date you need the money.
- Pick the category that fits that horizon.
- Start a SIP you can sustain through a bad year.
Read Also:
Why multi-asset funds are your best bet amid market fluctuations?
8 Safe Low Risk Investment Options in India for Salaried Investors
20 Money Investment Ideas: Smart Ways to Grow Your Wealth in 2026
How are Multi Asset Funds Taxed in 2026?
Multi-asset fund tax depends on average equity exposure. At 65% or more, it is taxed as equity: 20% short-term and 12.5% long-term above ₹1.25 lakh after 12 months. Below 65%, long-term gains are taxed at 12.5% with no exemption and short-term gains at slab rate. Confirm with the latest notification.
| Average equity exposure | STCG | LTCG | Holding for LTCG |
| 65% or more | 20% (Section 111A) | 12.5% above ₹1.25 lakh (Section 112A) | 12 months |
| 35% to 65% | Slab rate | 12.5%, no ₹1.25 lakh exemption | 24 months (per published guides, confirm) |
Scenario math. Take a gain of ₹2,00,000 with no other capital gains that year:
- Fund with 65%+ equity, held 18 months: taxable amount is ₹75,000, so tax is ₹9,375.
- Fund with 35% to 65% equity, held 25 months: tax is ₹25,000.
The gap is ₹15,625, before cess, for the same gain. Always check the actual equity allocation in the factsheet, not the fund name. Tax is applied at the fund level, so you do not pay separate tax on the gold portion.
As of 2026. Rates and holding periods can change; confirm with the Income Tax Department.
Multi-asset fund or DIY mix: which costs more tax when you rebalance?
A multi asset fund usually costs less tax when rebalancing, because the manager shifts between equity, debt and gold inside the scheme without creating a taxable event for you. In a DIY portfolio, each sale of equity, a gold ETF or a debt fund can trigger capital gains tax.
Scenario math. Your DIY portfolio has gold ETF units that rose, and you sell ₹1 lakh worth to restore balance. If ₹40,000 of that is gain held over 12 months, LTCG at 12.5% means ₹5,000 tax, with no ₹1.25 lakh exemption for gold ETFs. The same shift inside a multi-asset fund creates no tax for you until you redeem.
The trade-off: you rely on the manager and pay fund costs. A DIY investor can also rebalance with fresh SIP money and avoid selling at all.
Frequently Asked Questions
Is a multi asset fund safe if the stock market crashes?
A multi asset fund falls less than a pure equity fund in most crashes, but it is not safe from losses. Gold and debt cushion the fall, yet an equity-led scheme can still drop 10% or more. Check the fund’s equity share and maximum drawdown before investing.
Why did my multi-asset fund fall when gold went up?
A multi-asset fund can fall even when gold rises if equity is its largest holding. Gold often forms 10% to 25% of the portfolio, while equity can be 50% to 80%. A sharp equity decline can outweigh the gold gain. Check the current asset mix in the monthly factsheet.
Is a multi-asset fund taxed as equity or debt?
It depends on average equity exposure. A fund holding 65% or more in equity is taxed as an equity fund. Below that, hybrid rules apply, with long-term gains at 12.5% and no exemption. The gold portion is not taxed separately. Confirm rates with the latest notification.
Should I stop my multi-asset SIP after gold and silver rallied in 2025?
Stopping a SIP because of one year’s rally is usually market timing in disguise. A multi asset fund rebalances automatically, so it may already have trimmed gold. Review the fund’s current asset mix and your goal horizon before changing anything. Do not stop only because of recent returns.
Can I hold two multi asset funds together?
You can, but overlap is likely. Both funds may hold similar equity names and gold exposure, so you gain little extra diversification and add tracking effort. Compare the top holdings and asset mix first. One well-chosen fund often does the job.
Does a multi asset fund replace my emergency fund?
No. A multi-asset fund holds equity, so its value can fall exactly when you need cash. Keep emergency money in liquid or savings options. Use multi-asset funds for goals at least 3 to 5 years away.
How long should I stay invested in a multi asset fund?
Plan for at least 5 years. Multi-asset funds hold equity and gold, which can swing sharply in single years, as 2025 showed. A longer holding period lets rebalancing work and also helps you cross the tax holding thresholds (12 or 24 months, depending on equity share).
Disclaimer
Mutual fund investments are subject to market risks. Read all scheme related documents carefully. Past performance is not indicative of future returns. Figures cited are from third-party sources as of the dates mentioned and may change. Tax rules are as of 2026; confirm with the latest Income Tax Department notification or a tax advisor. This article is for education and is not investment advice or a recommendation of any scheme. Wealth Redefine Financial Services LLP is an AMFI-registered Mutual Fund Distributor (ARN: 167127).