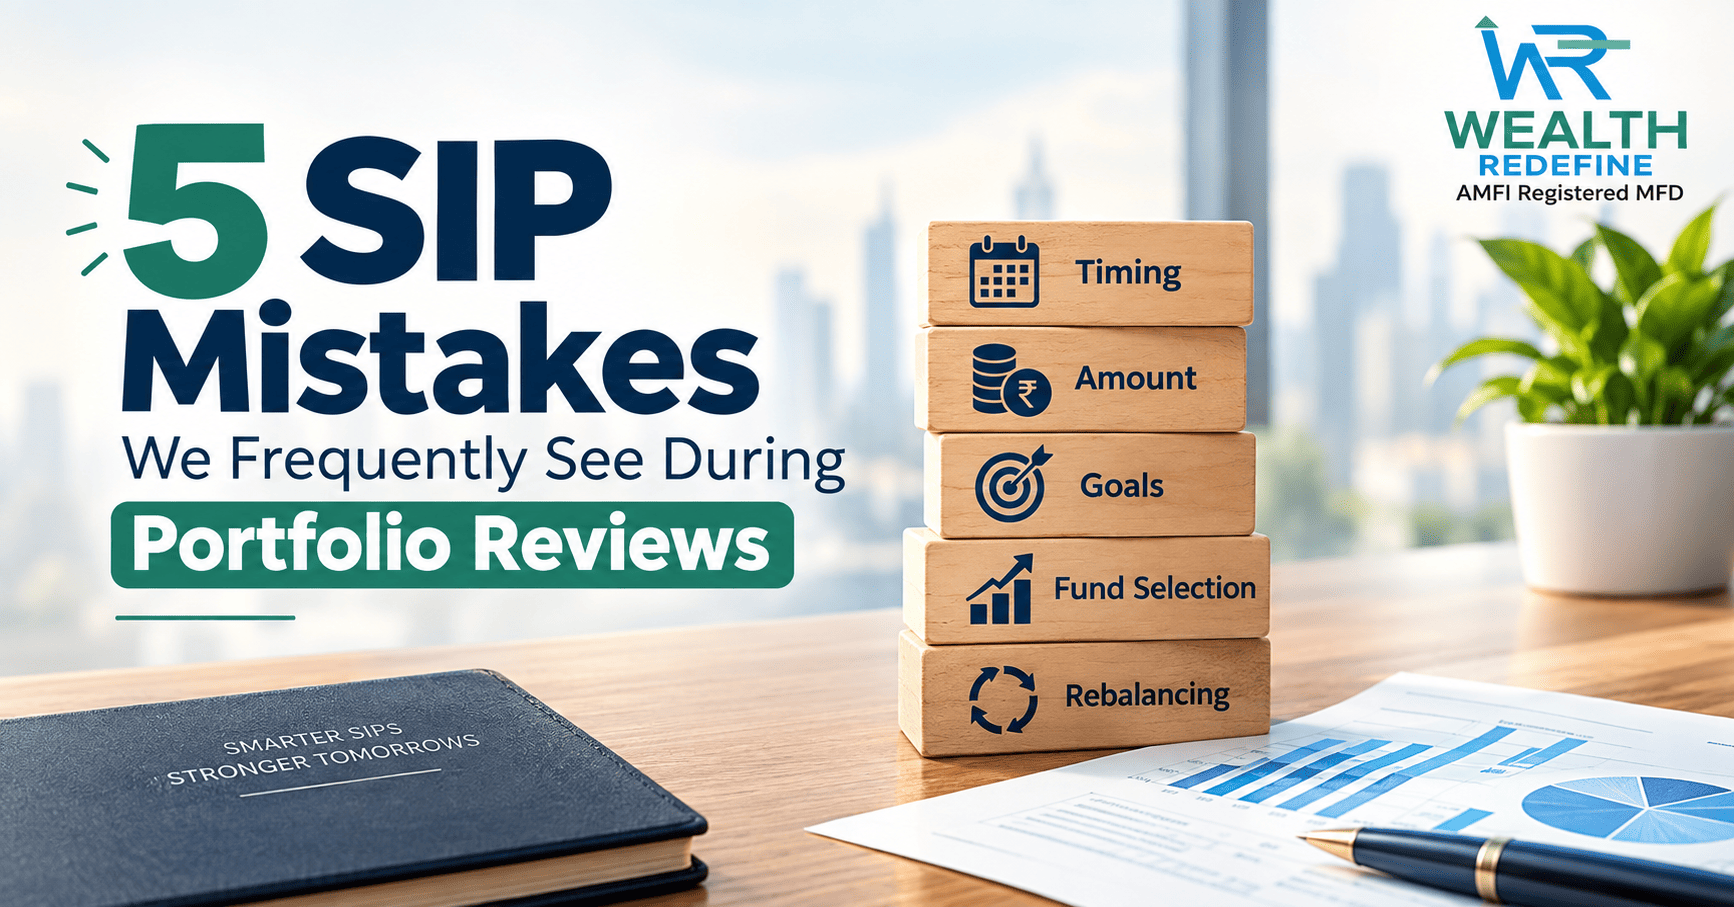
Every quarter, the same story plays out across our portfolio review desk: someone has been investing carefully for years, but they are saving cash, not growing wealth. SIP mistakes are not about the investor’s laziness — they’re about decisions that quietly compound into underperformance, such as avoiding the lowest prices during market drops or owning multiple mutual funds that buy the same stocks.
This blog walks through the five mutual fund portfolio review mistakes we see most often, why they happen even to disciplined investors, and exactly how to fix them.
If you’ve never sat through a formal portfolio review, here’s what usually happens: an advisor pulls up your consolidated account statement, lines up every fund you own against your actual life goals, and asks one uncomfortable question — “What is this SIP actually for?” More often than not, there’s a long pause before an answer arrives. That pause is where these mistakes live.
Mistake 1: Goal-less Investing
Why it looks right initially:
Starting a SIP(Systematic Investment Plan) without a defined goal feels productive. You’re saving, the amount is on auto-debit mode, the NAV is increasing, and your bank balance looks more manageable by December than it did in January. For the first two or three years, goal-less investing is practically indistinguishable from goal-based SIP planning — the account balance grows either way, and nobody questions a growing number.
The portfolio review damage:
The problem surfaces the moment life asks for money. A child’s admission fee, a down payment, a medical emergency — without a mapped timeline, every fund in the portfolio is equally “available,” which usually means the investor redeems whatever fund has grown the most, regardless of whether that fund was meant for a 3-year goal or a 20-year one.
During a portfolio review, we frequently find equity SIPs meant to fund a wedding three years away sitting in the same basket as retirement corpus. Without goal based SIP planning, there’s no way to judge whether you’re actually on track — you’re just watching a number move up and down with no reference point.
Mistake 2: Owning Multiple Mutual Funds
Owning 10+ funds for safety:
If you talk about retail investing, “more funds equals more safety” is one of the most persistent myths. At Wealth Redefine, we regularly review portfolios with 12, 15, even 18 mutual fund schemes, built up one recommendation, one WhatsApp forward, one “hot fund” article at a time. The investor’s logic is understandable — diversification is genuinely good advice, so surely more of it is better. This is where over-diversification in mutual funds becomes its own risk, not a hedge against one.
Portfolio overlap reality check:
Run any 12-fund portfolio through an overlap tool, and the result is almost always the same: five or six of those “different” funds are quietly holding the similar top 15-20 large-cap stocks. You’re paying multiple expense ratios, tracking multiple fund managers, and receiving multiple long capital gains statements — for what is, in effect, one diversified equity bet wearing different labels.
A cleaner portfolio review usually consolidates 15 funds down to 5-6 well-chosen ones across current categories, without sacrificing genuine diversification. Fewer funds, tracked properly, beat many funds tracked loosely.
Mistake 3: Chasing Last Year’s Toppers
Style drift and cyclical traps:
Many investors chase past returns in fund selection, which is the single most common mistake when a portfolio review turns uncomfortable for mutual funds. An investor sees a fund topping the “Best Mutual Funds of the Year” list, switches their SIP into it, and is disappointed a year later when it’s nowhere near the top anymore. This isn’t bad luck — it’s how market cycles work.
A small-cap fund that outperformed during a bull run typically did so because of style concentration (a sector tilt, a size bias, a specific theme) that becomes a headwind once the cycle rotates.
Mistake 4: Hitting the Panic Button During Market Dips
Rupee-cost averaging interruption:
Every meaningful market correction sends the same message into your inbox: “Should I stop my SIP until things stabilize?” The instinct to stop SIPs during market dips feels emotionally logical but is financially costly. The entire mathematical advantage of a SIP comes from rupee-cost averaging — buying more units when prices are low and fewer when prices are high, so your average purchase cost smooths out over time.
If you pause your SIP during a market correction does the opposite of what you wanted: it removes you from the market exactly when units are cheapest, and it’s usually followed by an attempt to “time the re-entry,” which rarely works as planned. In portfolio reviews conducted right after a market fall, accounts that paused their SIPs consistently show a lower long-term XIRR than those that stayed the course—sometimes by automating a top-up instead.
Mistake 5: Skipping the Step-Up
Inflation deficit calculation:
A flat SIP amount that never changes is a step-up SIP error hiding in plain sight. If you started a ₹10,000 monthly SIP five years ago and haven’t increased it since, you haven’t actually maintained your saving rate — you’ve quietly reduced it, because ₹10,000 buys less of your future goal today than it did when you started, thanks to inflation and, in most cases, a rising income.
Run the maths on almost any long-term goal, and a flat SIP falls meaningfully short of the same SIP stepped up by even 10% annually. The step-up feature exists in nearly every SIP mandate today; the mistake isn’t the absence of the tool, it’s simply forgetting to use it.
The Portfolio Review Framework: How to Fix These Today
Step 1: The “Cash-Today” sanity test
Pull up your full portfolio and ask, honestly: “If I had to convert every single holding to cash today, would I be comfortable with that outcome for my every goal?” This single test exposes goal-less investing and over-diversification in mutual funds problems immediately, because it forces every holding to justify its presence. A fund you can’t explain the purpose of is a fund that needs a decision — hold, consolidate, or exit.
Step 2: Mapping SIPs to timeline horizons
Next, tag every SIP against a specific goal and a specific number of years to that goal. Short-horizon goals (under 3 years) generally have no business sitting in pure equity; medium-horizon goals (3-7 years) need a hybrid approach; only genuinely long-horizon goals (7+ years) should carry the bulk of equity SIP exposure.
Once every rupee has a destination and a deadline, goal based SIP planning stops being a slogan and becomes an actual filter for every future investment decision — including whether to step up, whether to hold through a dip, and whether that 13th fund really deserves a place in your portfolio.
A portfolio review isn’t a one-time event; it’s a discipline. Revisiting your funds against this framework once or twice a year is usually enough to catch these five mistakes before they cost you a meaningful chunk of your long-term returns.
Read Also:
Best One Time Investment Plan With High Returns: A Complete Guide
Money Investment Ideas: Smart Ways to Grow Your Wealth in 2026
FAQ
Q1. How often should I do a mutual fund portfolio review?
Most investors are well served by a review every six months, or after any major market movement, income change, or life event (marriage, home purchase, childbirth).
Q2. Should I stop my SIP when the market falls?
Generally no. Rupee-cost averaging is designed to work in your favour during corrections. A pause typically hurts long-term returns more than the temporary discomfort of a falling NAV.
Q3. How many mutual funds should I ideally hold?
For most retail investors, 4-7 well-selected funds across categories (large-cap, flexi-cap/multi-cap, mid/small-cap, and debt/hybrid where relevant) offer sufficient diversification without unnecessary overlap.
Final Thought
So, these were the SIP mistakes that we found during the investor’s portfolio review. I hope you just got about which mistakes make your portfolio very weak. If you still have any queries, feel free to contact us.